Build · Institutions of One × Fashion
Build study · Practice before entity
Can a Creator Build a House Before Building a Company?
A creator can build institutional capacity before forming a company—method, evidence, relationships, audience routes, promises, and an archive—but should never confuse that capacity with legal personality, liability protection, tax status, or governance.
Read the story00
The proposition
The word “house” can describe a cultural practice long before it describes a particular legal entity. A person may already have recurring clients, collaborators, methods, files, samples, domains, social accounts, invoices, licenses, obligations, and a public promise. Those elements form an institution in the editorial sense because they coordinate action and memory. They do not automatically create a corporation, limited-liability shield, employer system, or transferable bundle of rights.
The Small Business Administration’s current guidance distinguishes business structures and explains that structure affects taxes, liability, paperwork, and fundraising. Its registration guidance also makes the requirements contingent on structure, activity, and location. These sources do not select an entity for a fashion creator. They establish why the editorial and legal thresholds must remain separate—and why early institutional discipline makes later professional advice more useful.
01–04
The institutional sequence
01 · PRACTICE
What already repeats?
Document the offer, client or audience promise, research method, design sequence, collaborator roles, quality threshold, payment path, correction route, and archive habit. Repetition reveals the institution already operating around the person.
Sources behind this section
An interpretation drawn from the linked records.
02 · RECORD
Can the practice prove what happened?
Use written scopes, invoices, contributor credits, versioned files, rights and permissions records, contact consent, expense evidence, tax records, and object identifiers appropriate to the actual jurisdiction and activity.
Sources behind this section
An original working method informed by the linked records.
03 · SEPARATE
Which formal questions cannot be solved by good habits?
Entity formation, liability, tax treatment, employment, insurance, securities, licenses, registrations, beneficial ownership, contracting authority, and cross-border activity require fact-specific professional review. A beautiful archive does not create a liability shield.
Sources behind this section
Directly supported by the linked records.
04 · TRANSITION
What should move when structure arrives?
Inventory names, domains, accounts, agreements, equipment, files, marks, designs, licenses, debts, receivables, privacy obligations, and archive custody. Counsel and advisers must determine what can be assigned, licensed, contributed, retained, or newly contracted.
Sources behind this section
An original working method informed by the linked records.
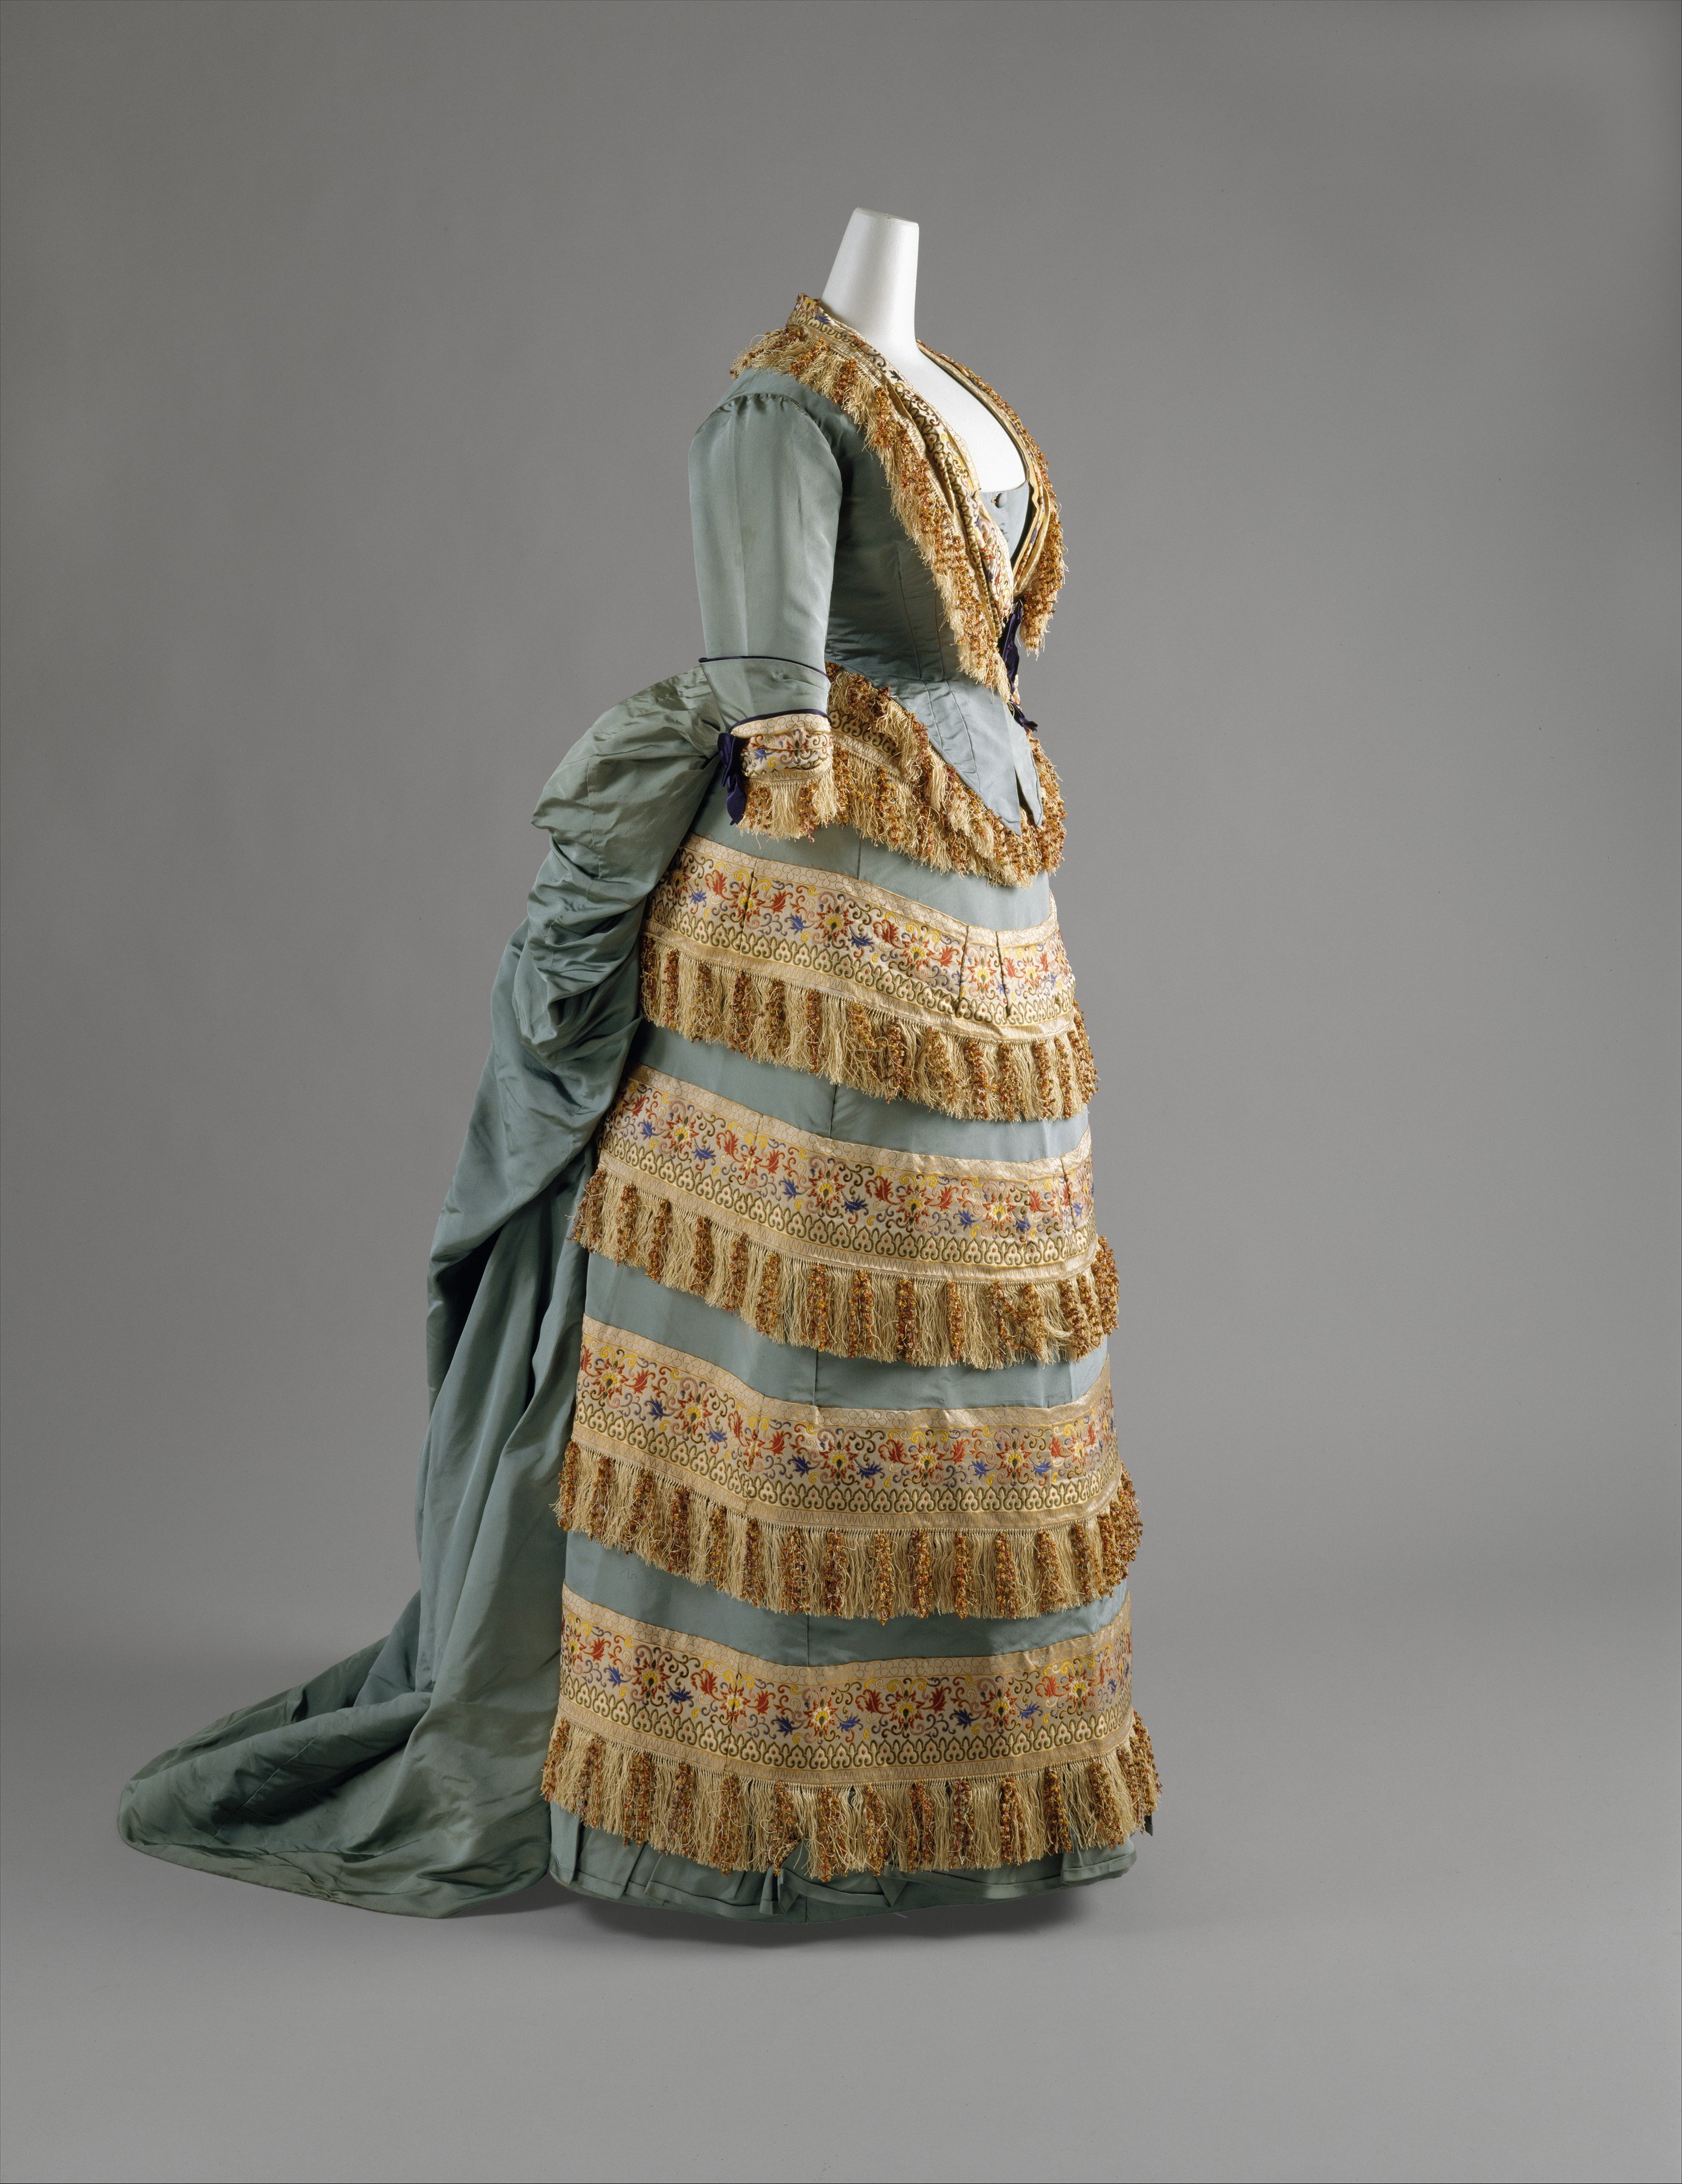
Look closely
Ball gown
House of Worth · ca. 1872 · Silk
This House of Worth gown survives under a house-level maker attribution, but the object record cannot tell us which entity structure, contracts, or liabilities operated at every moment. Cultural continuity and legal form require separate evidence.
Object record and image details
- Collection number
- 46.25.1a–d
- Credit
- Gift of Mrs. Philip K. Rhinelander, 1946
- Image terms
- Public Domain / Met Open Access
View the museum record ↗ · Download exhibition image ↓ · View the museum file ↗

COUNTERPOINT
What this framework could get wrong
Celebrating “institution before company” can romanticize informal work, delay protections, conceal unpaid labor, or expose the creator and collaborators to avoidable risk. The point is not to postpone advice. It is to arrive with a legible practice map—and to formalize when the facts, jurisdiction, liability, tax, labor, funding, and continuity needs require it.
FIELDWORK
Do the work now
Use this as a working session, not a score.
- Map every recurring promise, role, payment, file, account, right, obligation, and correction route already in use.
- Mark the person or entity currently named on each agreement, invoice, domain, account, registration, and insurance record.
- List every place where collaborators, customers, money, manufacturing, data, travel, or liability create a professional-review trigger.
- Take the transition inventory to qualified legal, tax, insurance, employment, and financial advisers in the relevant jurisdictions.
What the sources establish
The SBA distinguishes sole proprietorships, partnerships, LLCs, corporations, and cooperatives and notes that structure affects taxes, liability, paperwork, and fundraising.
Registration requirements vary by structure, activity, and location; formal entity creation is not identical to beginning a creative practice.
A creator can build methods, records, relationships, audience routes, and rights inventories before incorporation, but should not imply liability protection or legal status that does not exist.
Source note
An interpretation drawn from the linked records.
READ / WATCH / LOOK CLOSER
Continue the story
Choose a business structure
U.S. Small Business Administration · updated 2025-03-07
Open source ↗Source and use notes
Reference S94
Official general business guidance; paraphrase and link. Entity, tax, liability, and jurisdiction questions require professional advice.
LINK_ONLY
Register your business
U.S. Small Business Administration · updated 2025-03-07
Open source ↗Source and use notes
Reference S95
Official general guidance; paraphrase and link without representing it as state-specific legal or tax advice.
LINK_ONLY
Universal Electronic Records Management Requirements, Version 3
U.S. National Archives and Records Administration · 2023-06
Open source ↗Source and use notes
Reference S39
Government resource; link/download for education and do not imply endorsement.
LINK_ONLY
15 U.S.C. § 1060 — Assignment
U.S. House Office of the Law Revision Counsel · current preliminary edition
Open source ↗Source and use notes
Reference S49
U.S. statutory text; quote narrowly and link to the official current source.
QUOTE_LINK
THE OBJECTS
Look at the material record
Each object extends the question through a different silhouette, material, function, or moment.
FROM THE COLLECTIONBall gown
House of Worth · ca. 1872 · Silk
The house is visible as both maker attribution and an enduring cataloguing unit.
Object record and image details
- Collection number
- 46.25.1a–d
- Credit
- Gift of Mrs. Philip K. Rhinelander, 1946
- Image terms
- Public Domain / Met Open Access
- Origin
- Official institution collection record; independently catalogued, not AI-generated.
- Source
- View the museum record ↗
Download exhibition image ↓ · View the museum file ↗ · Download full image notes ↗
FURTHER READING
Archives, records, tools and learning
Universal Electronic Records Management Requirements, Version 3
U.S. National Archives and Records Administration · 2023-06
Open resource ↗Source and use notes
Reference S39
Government resource; link/download for education and do not imply endorsement.
LINK_ONLY
15 U.S.C. § 1060 — Assignment
U.S. House Office of the Law Revision Counsel · current preliminary edition
Open resource ↗Source and use notes
Reference S49
U.S. statutory text; quote narrowly and link to the official current source.
QUOTE_LINK
Choose a business structure
U.S. Small Business Administration · updated 2025-03-07
Open resource ↗Source and use notes
Reference S94
Official general business guidance; paraphrase and link. Entity, tax, liability, and jurisdiction questions require professional advice.
LINK_ONLY
Register your business
U.S. Small Business Administration · updated 2025-03-07
Open resource ↗Source and use notes
Reference S95
Official general guidance; paraphrase and link without representing it as state-specific legal or tax advice.
LINK_ONLY
Vestments and how to make them
Library of Congress · 1914
Open resource ↗Source and use notes
Reference X15
Library of Congress item identifies the work as free to use and reuse.
LINK_ONLY
A system for cutting ladies garments
Library of Congress · 1917
Open resource ↗Source and use notes
Reference X17
Library of Congress item identifies the work as free to use and reuse.
LINK_ONLY
Dressmaking
Internet Archive · 1917
Open resource ↗Source and use notes
Reference X43
Work-level public-domain-era candidate; Internet Archive availability alone is not file-level permission, so linked pending scan-source verification.
LINK_ONLY
Pattern making
Internet Archive · 1922
Open resource ↗Source and use notes
Reference X44
Work-level public-domain-era candidate; file provenance requires item review before local ingest.
LINK_ONLY
Drafting trousers for men, boys, women
Internet Archive · 1945
Open resource ↗Source and use notes
Reference X46
Item page displays Public Domain Mark 1.0; retained as a canonical resource rather than duplicating its derivative files.
LINK_ONLY
The Keystone jacket and dress cutter
Internet Archive · 1895
Open resource ↗Source and use notes
Reference X47
Public-domain-era work; linked pending exact derivative-file provenance verification.
LINK_ONLY
Sew your own: kimono-inspired dress
Victoria and Albert Museum · 2023; accessed 2026-09-07
Open resource ↗Source and use notes
Reference X50
First-party educational page; patterns and page media remain under their stated site conditions.
LINK_ONLY
Research notes for this chapter
Exhaustive within the 18-surface registry and recorded queries; not a claim to every item on the internet.
- Places searched
- 18
- Records considered
- 12
- Images available for use
- 1
- Further-reading links
- 11
Stopped after all 18 named surfaces were queried on 2026-09-07; qualifying records were retained, exact duplicate URLs and assets were removed, every reusable file was checked at work and file level, and remaining no-result surfaces were named. New records or changed rights statements reopen the report.
Download detailed research notes ↓ · Read how the collection was assembled
FOLLOW THE QUESTION
One inquiry, six forms
- Canonical essay: The House Before the Company
- Eleven-minute practice-to-structure film
- Ten-frame institution-is-not-entity carousel
- Five founder-readiness vertical scripts
- Pre-Entity Institution Map
- Newsletter, adviser-prep, and workshop editions
By RN Collins.
Download the chapter ↓ · Download source notes ↓
Practical and professional boundaries
Recorded performance, bespoke RN photography, participant releases, and counsel or specialist review are separate human-led work. They are not represented here as completed recordings, permissions, or professional opinions.
FIND IT ELSEWHERE
Where this dossier lives
How to read the source notes
Material statements link to the records behind them. Interpretation is not presented as source fact. Legal sections identify their jurisdiction; state, foreign, contractual, beneficial-ownership, validity, priority, and disputed-fact questions require appropriate professional review. This exhibition is educational and does not provide legal, conservation, or business advice.